Buy fiduciaire.eu ?
We are moving the project
fiduciaire.eu .
Are you interested in purchasing the domain
fiduciaire.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy fiduciaire.eu ?
What are closing entries in accounting?
Closing entries are journal entries made at the end of an accounting period to transfer the balances of temporary accounts (revenue, expenses, and dividends) to the retained earnings account. This process helps reset the temporary accounts to zero to prepare for the next accounting period. By closing these accounts, the company can start fresh with accurate financial statements for the new period. **
What are the booking entries in accounting?
Booking entries in accounting refer to the recording of financial transactions in the general ledger of a company. These entries include debits and credits to various accounts, such as assets, liabilities, equity, revenue, and expenses. The purpose of booking entries is to accurately reflect the financial position and performance of the company. This process ensures that all transactions are properly recorded and can be used to prepare financial statements and reports for internal and external stakeholders. **
Similar search terms for Entries
Top-Angebote
Products related to Entries:
-
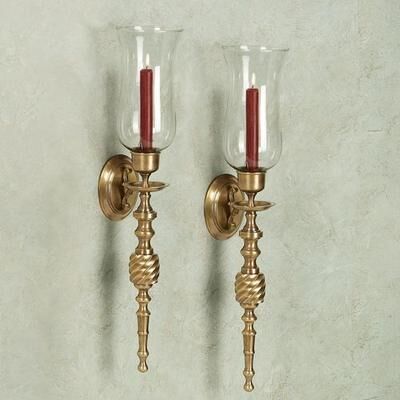
Flythe Consulting Jonetia Hurricane Wall Sconce Pair Satin Brass, Pair, Satin BrassThe Jonetia Satin Brass Hurricane Wall Sconce Pair proudly displays grandeur on your walls. These hand-forged, solid brass sconces feature a diamond design and fleur-de-lis motif. Sconces have a lacquered, satin brass finish that is done by hand. A...229,00 $*Shipping: 32,06 $Secure redirect to the provider


-
What are the booking entries in Accounting 2?
In Accounting 2, booking entries refer to the process of recording financial transactions in the general ledger. These entries include debits and credits to various accounts to accurately reflect the impact of the transaction on the company's financial position. Booking entries are essential for maintaining accurate financial records and ensuring that the company's financial statements are prepared in accordance with generally accepted accounting principles. These entries are typically made using double-entry accounting, where each transaction affects at least two accounts with equal and opposite debits and credits. **
-
What is the topic of journal entries in accounting?
The topic of journal entries in accounting is to record the financial transactions of a business in chronological order. Journal entries are used to track the flow of money into and out of the business, as well as to ensure that the company's financial records are accurate and up-to-date. Each journal entry typically includes the date of the transaction, a description of the transaction, the accounts affected, and the amount of money involved. **
-
How do I book closing entries in industrial accounting?
In industrial accounting, closing entries are booked at the end of an accounting period to transfer the balances of temporary accounts (revenue and expense accounts) to the retained earnings account. To book closing entries, you need to first prepare an adjusted trial balance to ensure all revenue and expenses are properly recorded. Then, you can close the revenue accounts by debiting them and crediting the income summary account, and close the expense accounts by crediting them and debiting the income summary account. Finally, you can close the income summary account to the retained earnings account. **
-
Can you help me with booking entries in accounting?
Yes, I can help you with booking entries in accounting. Booking entries involves recording financial transactions in the appropriate accounts using double-entry accounting principles. I can assist you in understanding the different types of accounts, such as assets, liabilities, equity, revenue, and expenses, and how to properly record transactions in these accounts. Additionally, I can guide you through the process of creating journal entries, posting to the general ledger, and preparing financial statements. Let me know if you need any specific assistance with booking entries in accounting. **
What are the accounting entries in the field of accounting for inventory valuation?
In the field of accounting, inventory valuation involves recording the cost of goods held for sale. The accounting entries for inventory valuation typically include debiting the inventory account to reflect the cost of goods purchased or produced, and crediting the corresponding account such as accounts payable or cash. Additionally, adjustments may be made to account for any changes in the value of inventory, such as writing down inventory to its lower of cost or market value. These adjustments are recorded by debiting cost of goods sold and crediting inventory reserve or loss account. **
What are the journal entries in accounting for inventory valuation?
The journal entries in accounting for inventory valuation typically involve recording the cost of inventory on the balance sheet. When inventory is purchased, the entry would debit the inventory account and credit the accounts payable or cash account. When inventory is sold, the cost of goods sold account is debited and the inventory account is credited for the cost of the items sold. Additionally, adjustments may be made to the inventory account to reflect changes in the value of inventory, such as write-downs for obsolete or damaged goods. **
Top-Angebote
Products related to Entries:
-
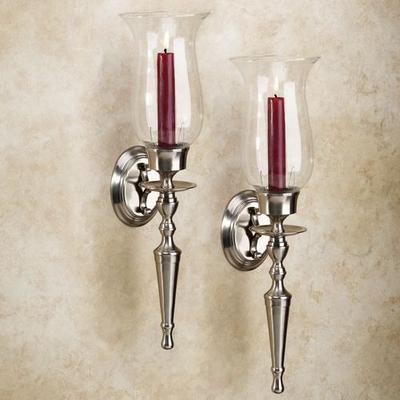
Flythe Consulting Arika Wall Sconce Pair, Pair, Satin NickelThe Arika Wall Sconce Pair is an adaptation of old-fashioned light fixtures, with an appealing design that will complement modern decor. The lacquered solid brass sconces have 4.75 dia.x7 H clear glass hurricanes that will protect your standard...179,00 $*Shipping: 22,95 $Secure redirect to the provider
-
Flythe Consulting Jonetia Hurricane Wall Sconce Pair Satin Brass, Pair, Satin BrassThe Jonetia Satin Brass Hurricane Wall Sconce Pair proudly displays grandeur on your walls. These hand-forged, solid brass sconces feature a diamond design and fleur-de-lis motif. Sconces have a lacquered, satin brass finish that is done by hand. A...229,00 $*Shipping: 32,06 $Secure redirect to the provider
-
What are closing entries in accounting?
Closing entries are journal entries made at the end of an accounting period to transfer the balances of temporary accounts (revenue, expenses, and dividends) to the retained earnings account. This process helps reset the temporary accounts to zero to prepare for the next accounting period. By closing these accounts, the company can start fresh with accurate financial statements for the new period. **
-
What are the booking entries in accounting?
Booking entries in accounting refer to the recording of financial transactions in the general ledger of a company. These entries include debits and credits to various accounts, such as assets, liabilities, equity, revenue, and expenses. The purpose of booking entries is to accurately reflect the financial position and performance of the company. This process ensures that all transactions are properly recorded and can be used to prepare financial statements and reports for internal and external stakeholders. **
-
What are the booking entries in Accounting 2?
In Accounting 2, booking entries refer to the process of recording financial transactions in the general ledger. These entries include debits and credits to various accounts to accurately reflect the impact of the transaction on the company's financial position. Booking entries are essential for maintaining accurate financial records and ensuring that the company's financial statements are prepared in accordance with generally accepted accounting principles. These entries are typically made using double-entry accounting, where each transaction affects at least two accounts with equal and opposite debits and credits. **
-
What is the topic of journal entries in accounting?
The topic of journal entries in accounting is to record the financial transactions of a business in chronological order. Journal entries are used to track the flow of money into and out of the business, as well as to ensure that the company's financial records are accurate and up-to-date. Each journal entry typically includes the date of the transaction, a description of the transaction, the accounts affected, and the amount of money involved. **
Similar search terms for Entries
-
How do I book closing entries in industrial accounting?
In industrial accounting, closing entries are booked at the end of an accounting period to transfer the balances of temporary accounts (revenue and expense accounts) to the retained earnings account. To book closing entries, you need to first prepare an adjusted trial balance to ensure all revenue and expenses are properly recorded. Then, you can close the revenue accounts by debiting them and crediting the income summary account, and close the expense accounts by crediting them and debiting the income summary account. Finally, you can close the income summary account to the retained earnings account. **
-
Can you help me with booking entries in accounting?
Yes, I can help you with booking entries in accounting. Booking entries involves recording financial transactions in the appropriate accounts using double-entry accounting principles. I can assist you in understanding the different types of accounts, such as assets, liabilities, equity, revenue, and expenses, and how to properly record transactions in these accounts. Additionally, I can guide you through the process of creating journal entries, posting to the general ledger, and preparing financial statements. Let me know if you need any specific assistance with booking entries in accounting. **
-
What are the accounting entries in the field of accounting for inventory valuation?
In the field of accounting, inventory valuation involves recording the cost of goods held for sale. The accounting entries for inventory valuation typically include debiting the inventory account to reflect the cost of goods purchased or produced, and crediting the corresponding account such as accounts payable or cash. Additionally, adjustments may be made to account for any changes in the value of inventory, such as writing down inventory to its lower of cost or market value. These adjustments are recorded by debiting cost of goods sold and crediting inventory reserve or loss account. **
-
What are the journal entries in accounting for inventory valuation?
The journal entries in accounting for inventory valuation typically involve recording the cost of inventory on the balance sheet. When inventory is purchased, the entry would debit the inventory account and credit the accounts payable or cash account. When inventory is sold, the cost of goods sold account is debited and the inventory account is credited for the cost of the items sold. Additionally, adjustments may be made to the inventory account to reflect changes in the value of inventory, such as write-downs for obsolete or damaged goods. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.